
- Ready now
- Featured
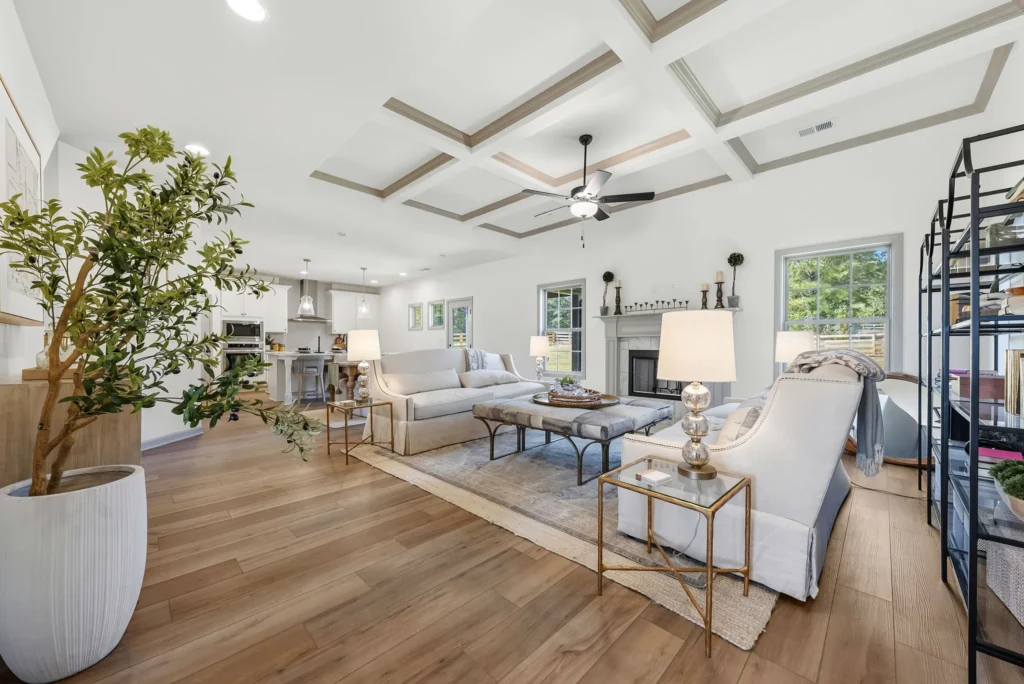
Jackson in Mountain Point Villas, 98 Hawkeye Trail
$529,900
98 Hawkeye Trail, Fortson, GA 31808
- 5 beds
- 4 baths
- 3,324 sq ft
3-2-1 Rate Buydown or up to $25K Flex Cash
A temporary 3-2-1 buydown or up to $25,000 in Flex Cash on select move-in-ready homes across Alabama and Georgia.
Your interest rate starts lower and steps up once a year for three years, so your monthly payment begins lighter while you settle into your new home.
Year 1 3.99% interest rate 7.770% APR*
You get up to $25,000 in Flex Cash.** Hughston Homes pays for the buydown out of it, and whatever the buydown doesn’t use can go toward closing costs and more. Both are available only on select move-in-ready homes when you finance with our preferred lender.
Find a Move-In Ready Home Talk with our team
Visit a model home this season. See model home hours
In partnership with CMG Home Loans
Your holiday incentive
Use your Flex Cash for a lower rate for your first three years, or put up to $25,000 toward what helps you most. If the buydown costs less than $25,000, you can use the rest too.
Both are available only on select move-in-ready homes when you finance with our preferred lender.
Your rate, year by year
For example, take this FHA 30-year fixed loan with a temporary 3-2-1 buydown. Rates are as of 10/23/2026 and subject to change.*
Year 1
3.99% Interest rate
7.770% APR
Year 2
4.99% Interest rate
7.770% APR
Year 3
5.99% Interest rate
7.770% APR
Years 4–30
6.99% Fixed note rate
7.770% APR
FHA 30-year fixed loan at 6.99% (7.770% APR) with a 3.5% down payment and a loan amount of $540,038, which includes the 1.75% upfront mortgage insurance premium. Payments shown are principal and interest only. Mortgage insurance, taxes and homeowners insurance are not included, so your actual payment will be higher.
As a result, year 1 is $1,014 a month less than the full note-rate payment.
Open to all loan types · minimum 680 credit score
How it works
A 3-2-1 buydown lowers your interest rate for the first three years of your loan. However, every buyer qualifies at the full 6.99% note rate, whatever the loan type, and your loan stays a 30-year fixed loan the whole time. Hughston Homes pays for the temporary buydown out of your Flex Cash at closing, and it must be written into your purchase contract.
First, your rate sits three percentage points below your fixed note rate in year 1.
Your rate steps up one point, so your monthly payment grows gradually instead of all at once.
One more step, then from year four on you pay your fixed note rate for the rest of the loan.
Eligible homes
Use up to $25,000 in Flex Cash on these homes for the buydown, closing costs or both when you finance with our preferred lender. Also, each home’s page lists its community’s sales agent and model home hours.
18 homes in 10 areas
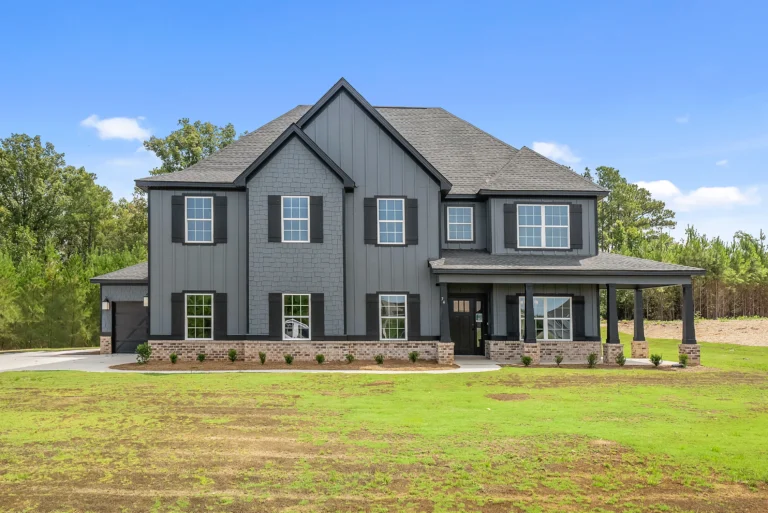
$529,900
98 Hawkeye Trail, Fortson, GA 31808
3-2-1 Rate Buydown or up to $25K Flex Cash
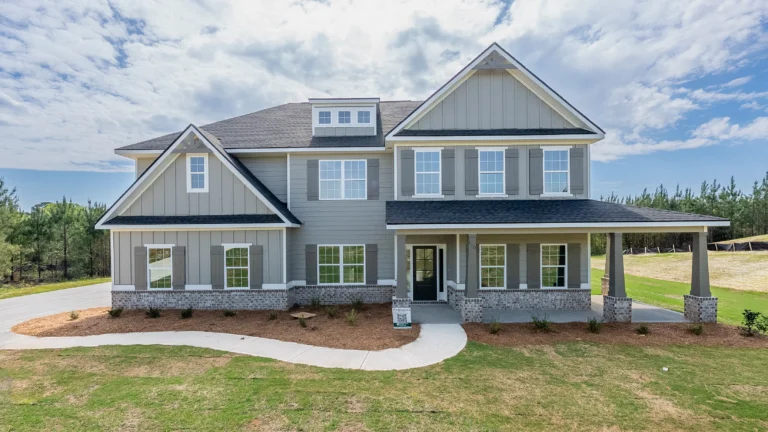
$534,900
74 Mitchell Road, Fortson, GA 31808
3-2-1 Rate Buydown or up to $25K Flex Cash
$564,900
110 Hawkeye Trail, Fortson, GA 31808
3-2-1 Rate Buydown or up to $25K Flex Cash

$574,900
183 Hawkeye Trail, Fortson, GA 31808
3-2-1 Rate Buydown or up to $25K Flex Cash
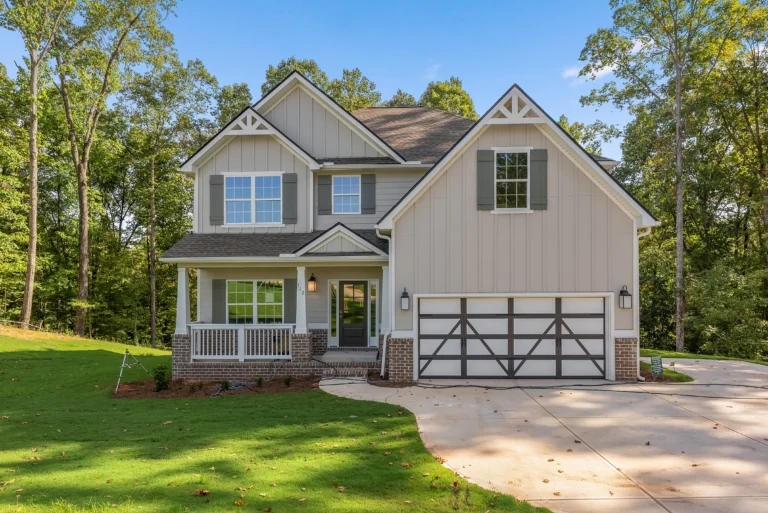
$514,900
112 Ironwood Way, Midland, GA 31820
3-2-1 Rate Buydown or up to $25K Flex Cash
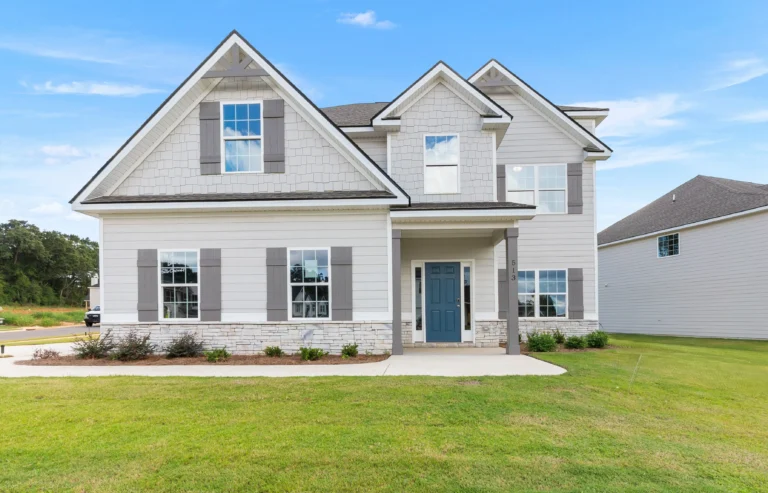
$390,400
513 O'Brien Drive, Kathleen, GA 31047
3-2-1 Rate Buydown or up to $25K Flex Cash
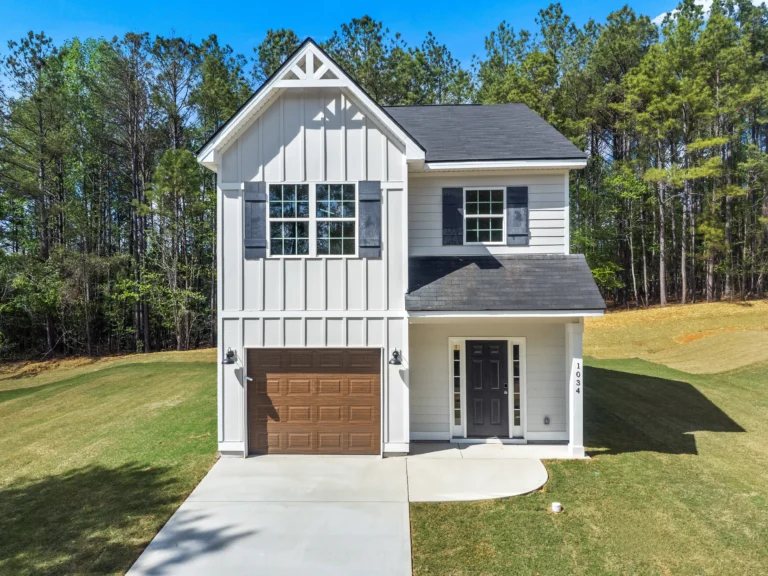
$249,900
1034 Sun Valley Court, Macon, GA 31211
3-2-1 Rate Buydown or up to $25K Flex Cash
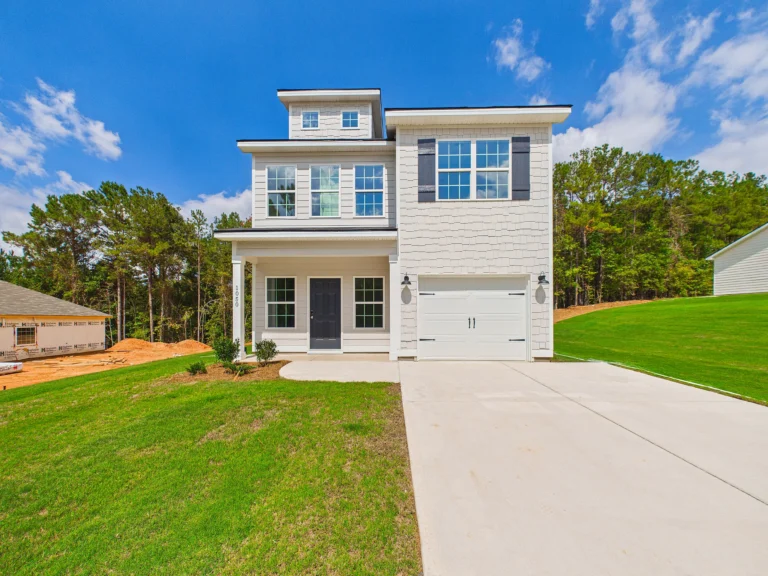
$284,900
1050 Sun Valley Court, Macon, GA 31211
3-2-1 Rate Buydown or up to $25K Flex Cash

$304,900
1046 Sun Valley Court, Macon, GA 31211
3-2-1 Rate Buydown or up to $25K Flex Cash
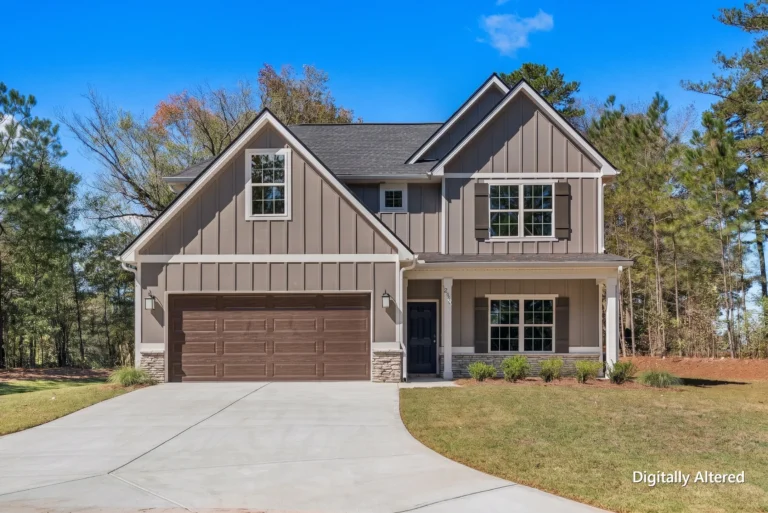
$389,900
5560 N. Hwy 29, Newnan, GA 30265
3-2-1 Rate Buydown or up to $25K Flex Cash
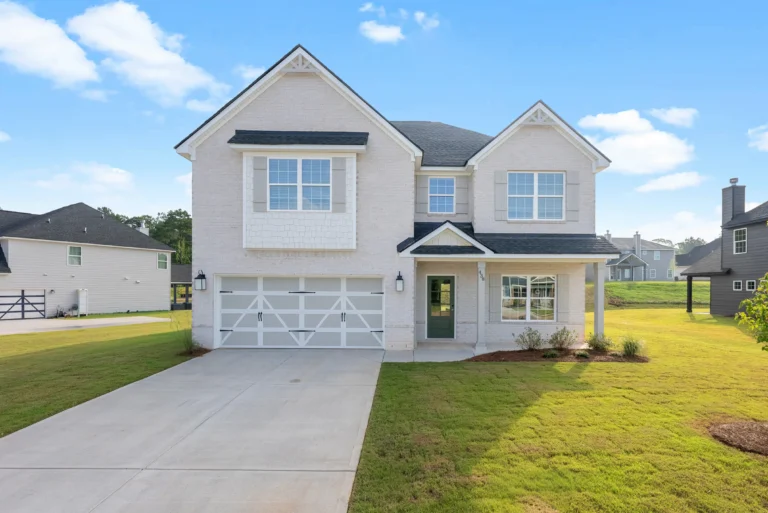
$394,900
438 Lakeview Way, LaGrange, GA 30241
3-2-1 Rate Buydown or up to $25K Flex Cash

$434,900
101 Beaver Creek Way, LaGrange, GA 30241
3-2-1 Rate Buydown or up to $25K Flex Cash
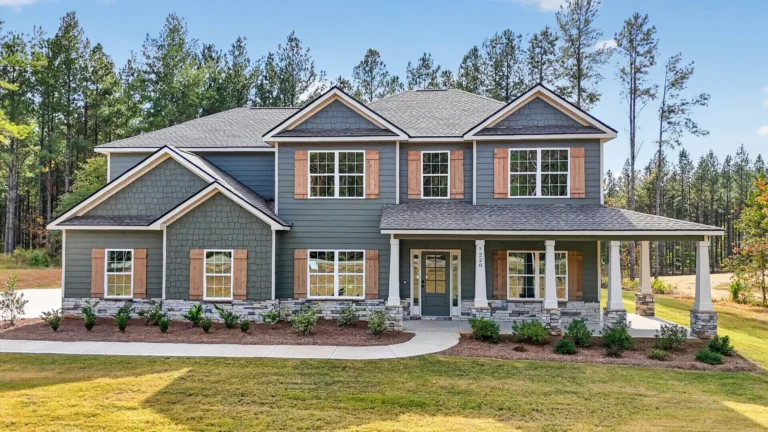
$614,900
7220 Bill Dorn Road, Appling, GA 30802
3-2-1 Rate Buydown or up to $25K Flex Cash
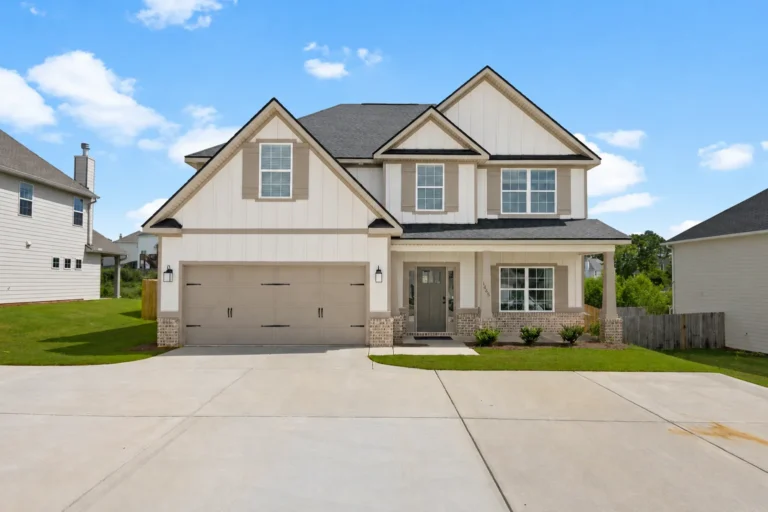
$449,900
1465 Academy Drive, Auburn, AL 36830
3-2-1 Rate Buydown or up to $25K Flex Cash
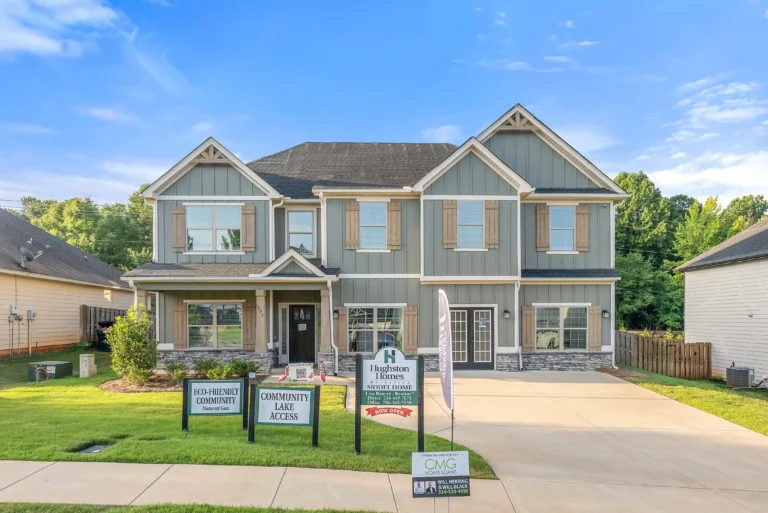
$539,900
1795 Solamere Court, Auburn, AL 36832
3-2-1 Rate Buydown or up to $25K Flex Cash

$464,900
3003 Wymond Drive, Opelika, AL 36804
3-2-1 Rate Buydown or up to $25K Flex Cash

$338,400
6 Liberty Place, Ft. Mitchell, AL 36856
3-2-1 Rate Buydown or up to $25K Flex Cash

$429,900
6 McLendon Road, Ft. Mitchell 36856
3-2-1 Rate Buydown or up to $25K Flex Cash
Tell us where you’d like to live and our team will send you the homes eligible for the 3-2-1 buydown or Flex Cash. We can also help you compare the two offers and connect you with our preferred lender.
Prefer to talk? Call our main office (706) 568-7650
Prefer to look in person? See model home hours
Financing questions? Stephen Templeton Branch Manager, CMG Home Loans (407) 921-9008 stempleton@cmghomeloans.com NMLS# 576636 · Look it up on NMLS Consumer Access
You are not required to use our preferred lender to purchase a Hughston Home.
Questions
A financing incentive that lowers your interest rate by three points in year one, two points in year two and one point in year three. Then, from year four through the end of the loan, you pay the fixed note rate.
The move-in-ready homes listed above, in Georgia and Alabama. Look for “3-2-1 Rate Buydown or up to $25K Flex Cash” on a home’s card, or ask our team. Homes must close by December 30, 2026.
All loan types are eligible, including conventional, FHA and VA loans, with a minimum credit score of 680, through our preferred lender, CMG Home Loans. The payment example on this page uses an FHA loan.*
Your rate settles at the fixed note rate for the rest of your 30-year loan. It doesn’t change after that, so your principal and interest payment stays the same.
Yes, when the buydown costs less than $25,000. Hughston Homes pays for the buydown out of your Flex Cash, and what’s left can go toward closing costs, prepaids or upgrades, as your loan program allows. You can also skip the buydown and put all of your Flex Cash toward those costs or a rate buydown of your choice.
Up to $25,000 can go toward a rate buydown, closing costs, prepaids like taxes and insurance, or upgrades, as your loan program allows.**
To receive the buydown or Flex Cash, yes. However, you are not required to use our preferred lender to purchase a Hughston Home.
 Equal Housing Opportunity
*Rates provided 10/23/2026. FHA Payment example: Stated rate may change or may not be available at time of rate lock. If you bought a $550,000 home with a 30 year loan at a fixed rate of 6.99% (7.770% Annual Percentage Rate), with a down payment of 3.5%, for a loan amount of $540,038 (includes upfront mortgage insurance premium of 1.75% of the loan amount), and a 3/2/1 Temporary Buydown you would make 12 monthly payments of $2,575, 12 monthly payments of $2,896, 12 monthly payments of $3,234 and 324 monthly payments of $3,589. Payment stated does not include mortgage insurance, taxes and homeowners insurance, which will result in a higher payment. The temporary buydown is available on all loan types with a minimum credit score of 680.
**Flex Cash of up to $25,000 is available on select Hughston Homes move-in-ready homes with the use of our preferred lender and may be applied toward an interest rate buydown, closing costs, prepaids or upgrades, as permitted by the loan program. When the 3-2-1 temporary buydown is chosen, its cost is paid from Flex Cash, and any remaining Flex Cash may be applied to those other uses. Credit cannot exceed allowable seller concession limits.
Stephen Templeton, Branch Manager, NMLS# 576636 | Branch NMLS# 2476562 | Corporate NMLS# 1820. CMG Home Loans. Offers available only on select Hughston Homes move-in-ready homes in Alabama and Georgia that close by December 30, 2026, with the use of our preferred lender, and subject to change. You are not required to use our preferred lender to purchase a Hughston Home.
New homes in Georgia and Alabama
Hughston Homes is a Georgia and Alabama home builder with 27 communities in 12 markets.
© 2026 Hughston Homes, a brand of Edgar Hughston Builder, Inc. All rights reserved.